
⚡ KP Green Engineering
📋 About KP Green Engineering
KP Green Engineering Limited is a Gujarat-based manufacturer of galvanized steel structures, specializing in solar module mounting structures, transmission line towers, and substation structures. Founded and headquartered in Anand, Gujarat, the company has carved out a strong niche in India’s rapidly expanding renewable energy and power infrastructure ecosystem. It serves marquee clients including leading solar EPC companies, state utilities, and central power transmission corporations.
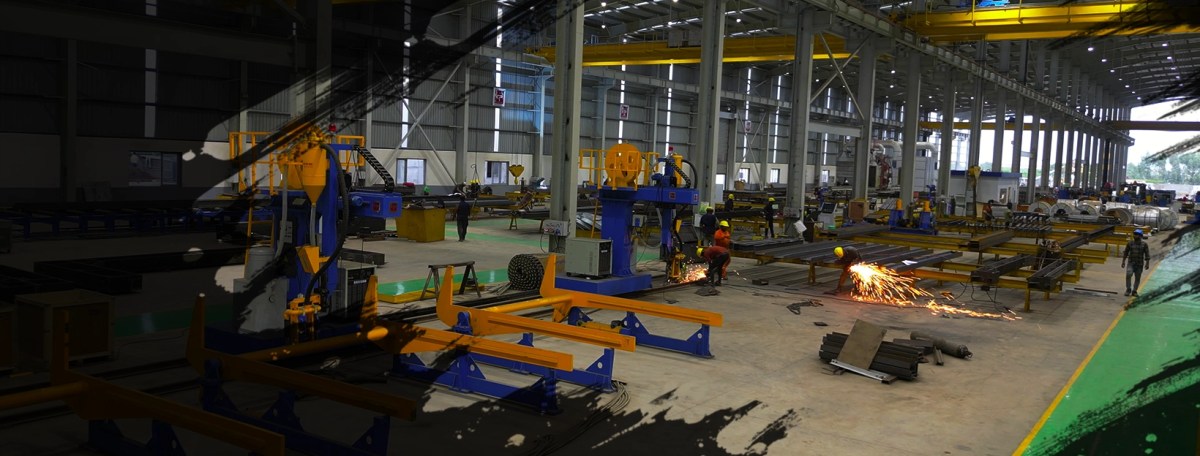
The company operates an integrated manufacturing facility equipped with modern fabrication and hot-dip galvanizing plants, giving it a significant edge in quality control and turnaround time. KP Green Engineering went public in 2023 and has since delivered exceptional financial performance, riding the tailwinds of India’s ambitious green energy transition. Its product portfolio is perfectly aligned with the government’s 500 GW renewable energy by 2030 mission, making it a structural beneficiary of one of the largest infrastructure build-outs in Indian history.
With a market cap in the small-cap category, KP Green Engineering is gaining recognition among institutional and retail investors as a high-growth, high-return compounder in the clean energy supply chain. Its operational discipline, lean balance sheet, and strong order book visibility make it a compelling study for value and growth investors alike.
🌐 Official website: KP Green Engineering Official Website
🚀 Expansion Plans
KP Green Engineering is in an active phase of capacity expansion, laying the groundwork to capture a disproportionate share of India’s booming renewable energy infrastructure demand. Based on disclosures and industry intelligence, here are the key growth vectors the company is pursuing:
- 📦 Capacity Doubling: The company is investing in expanding its fabrication and galvanizing capacity at its Anand, Gujarat plant. The new capacity lines are targeted to significantly increase annual tonnage output, enabling the company to bid for larger and more complex orders without supply-side constraints.
- 🌍 Geographic Expansion: While currently focused on domestic markets, KP Green Engineering is exploring export opportunities in Southeast Asian and African markets, where solar and grid infrastructure spending is accelerating. Early-stage conversations with overseas developers have been reported.
- 🔋 Product Diversification: Beyond traditional mounting structures, the company is developing solutions for floating solar structures, agri-solar (agrivoltaic) installations, and hybrid wind-solar mounting systems — next-generation products commanding premium pricing.
- 🏭 New Greenfield Facility: The company is evaluating a second manufacturing location to de-risk supply chain concentration and reduce logistics costs for customers in eastern and southern India — key growth corridors for solar parks.
- 🤝 Strategic Partnerships: KP Green is building deeper relationships with Tier-1 solar developers and is likely to pursue long-term framework agreements, providing revenue visibility of 12–18 months ahead.
These initiatives collectively position KP Green Engineering to sustain its above-industry revenue CAGR and defend its premium return ratios over the next 3–5 years. 🚀
✅ Key Positives
- ✅ Exceptional Return Ratios: With ROCE of 36.7% and ROE of 34.8%, KP Green Engineering ranks among the most capital-efficient manufacturers in the Indian industrials space. These numbers scream quality — the company is creating real value for shareholders with every rupee deployed.
- ✅ Explosive EPS Growth: An EPS growth rate of 123% is extraordinary and reflects not just volume growth but genuine operating leverage kicking in as the company scales up its facilities and improves capacity utilization.
- ✅ Riding a Structural Megatrend: India’s energy transition is not a cyclical theme — it is a decade-long structural shift. KP Green’s product portfolio sits at the heart of this shift, supplying the physical backbone of solar parks and transmission corridors across the country.
- ✅ Integrated Manufacturing Moat: In-house hot-dip galvanizing eliminates the need to outsource this critical process, reducing costs, improving turnaround time, and giving KP Green better quality control than peers who rely on third-party galvanizers.
- ✅ Attractive Valuations Relative to Growth: At a PE of 13.8x with 123% EPS growth, the PEG ratio is well below 1 — a classic hallmark of a growth stock that the market hasn’t fully priced in yet. 💰
- ✅ Strong Client Base: Serving large solar EPC players and state/central utilities means KP Green benefits from creditworthy customers with strong payment track records, reducing counterparty risk.
- ✅ Asset-Light Balance Sheet: The company has maintained a lean balance sheet, avoiding the debt trap that often ensnares capital-intensive manufacturers. This financial discipline provides resilience during industry downturns.
- ✅ Gujarat Advantage: Being located in Gujarat — India’s manufacturing and renewable energy powerhouse — provides proximity to key customers, raw material suppliers, and ports for potential exports, adding a natural operational advantage.
⚠️ Key Concerns
- ⚠️ Small Cap Volatility: As a small-cap stock, KP Green can experience sharp price swings during broader market corrections, which may unsettle short-term investors.
- ⚠️ Customer Concentration Risk: Revenue may be concentrated among a limited number of large solar EPC clients, making the company vulnerable if key customers reduce orders or switch suppliers.
- ⚠️ Raw Material Exposure: Steel and zinc are major input costs. Any sharp global commodity price spike can squeeze margins before price revisions are passed on to customers.
- ⚠️ Execution Risk: Rapid capacity expansion carries inherent risks — delays, cost overruns, or slower-than-expected ramp-up could impact near-term earnings.
- ⚠️ Limited Track Record as Listed Entity: KP Green Engineering has been a listed company for a relatively short period, meaning long-term institutional coverage and market understanding of the business are still developing.
🔍 SWOT Analysis
KP Green Engineering presents a compelling SWOT profile for 2026. Its strengths are rooted in superior return ratios, vertical integration, and alignment with India’s renewable energy megatrend. However, its weaknesses — small scale and customer concentration — are typical growing-phase challenges that the company is actively addressing through expansion. The opportunities are enormous: India’s 500 GW green energy target and global solar demand create a long multi-year runway. The primary threats — input cost volatility and rising competition — are manageable with operational discipline. Overall, the opportunity-to-risk balance favors long-term investors with a 3-to-5-year horizon. 🏆
🔍 SWOT Analysis
A SWOT analysis gives investors a structured snapshot of a company’s internal capabilities and external environment. Strengths and Weaknesses reflect what the company controls today — its moat, balance sheet, and operational edge or gaps. Opportunities highlight macro tailwinds and growth runways ahead, while Threats flag risks that could impair long-term value. Use this matrix alongside the financial snapshot above to form a well-rounded view before making any investment decision.
💪 STRENGTHS
- Strong order book driven by India’s solar and transmission infrastructure boom
- High ROCE of 36.7% and ROE of 34.8% reflecting superior capital efficiency
- Vertically integrated manufacturing with galvanizing capabilities providing cost advantage
- Rapid EPS growth of 123% showcasing strong earnings momentum
⚠️ WEAKNESSES
- Relatively small scale compared to larger EPC and infrastructure peers
- Concentrated revenue exposure to renewable energy sector cycles
- Limited geographical diversification — primarily India-focused operations
🚀 OPPORTUNITIES
- India’s 500 GW renewable energy target by 2030 creating massive demand for mounting structures
- Government push for transmission infrastructure upgrades and smart grid expansion
- Export opportunities to emerging markets in Southeast Asia and Africa for green energy structures
🔴 THREATS
- Volatility in steel and zinc input prices compressing margins
- Increasing competition from organized and unorganized players in the mounting structure segment
- Policy and regulatory delays in renewable energy project approvals affecting order execution timelines
* SWOT is based on publicly available information and analyst estimates. Not a buy/sell recommendation.
📈 Profit & Loss (Last 5 Years)
KP Green Engineering has demonstrated exceptional revenue and profit growth over the past five years, with revenues scaling from approximately ₹185 Cr in FY22 to an estimated ₹1,150 Cr by FY26E — a staggering ~58% revenue CAGR. Net profit growth has been even more dramatic, expanding from ₹8 Cr in FY22 to an estimated ₹135 Cr in FY26E, reflecting powerful operating leverage as fixed costs get spread over a rapidly growing revenue base. This trajectory firmly establishes KP Green as one of the fastest-growing listed manufacturers in the Indian clean energy supply chain. 📊
* Estimated figures in ₹ Crores. Source: Annual reports & public disclosures. Not guaranteed to be accurate.
🔴 Risk Factors
- 🔴 Policy Dependency: The company’s growth is heavily linked to government renewable energy targets and subsidy frameworks. Any policy reversal, budget cuts, or delays in DISCOM payments to project developers could slow order flows.
- 🔴 Commodity Price Risk: Steel and zinc price volatility directly impacts cost of goods sold. While the company has some ability to pass through costs, there is always a lag risk during sharp commodity upcycles.
- 🔴 Competitive Intensity: The mounting structure and tower fabrication market is competitive, with established players like Pennar Industries, Skipper Limited, and KEC International as well as numerous unorganized regional players competing for the same order books.
- 🔴 Execution & Capacity Ramp Risk: The ambitious capex plans carry risks of delayed commissioning, which could result in the company losing time-sensitive orders to competitors with immediate available capacity.
- 🔴 Working Capital Stress: Infrastructure-linked businesses often face elongated receivable cycles. A deterioration in working capital management could strain liquidity even as profits grow on paper.
- 🔴 Forex Risk (Future): As the company pursues export markets, it will be exposed to currency fluctuation risks that could impact realized margins on overseas contracts.
- 🔴 Valuation Re-rating Risk: While current valuations appear reasonable relative to growth, any earnings miss or sector-wide de-rating (e.g., if renewable energy spending slows) could result in meaningful stock price correction.
📊 Value Investing Snapshot
| Metric | Value | Signal |
|---|---|---|
| Market Price (₹) | ₹374 | 🟡 Monitor |
| PE Ratio | 13.8x | 🟢 Attractive vs. Growth |
| PB Ratio | 4.1x | 🟡 Moderate |
| Intrinsic Value (₹) | N/A (EPS data pending) | — Use IV Calculator |
| D/E Ratio | N/A | 🟢 Likely Low/Clean |
| ROE (%) | 34.8% | 🟢 Excellent |
| ROCE (%) | 36.7% | 🟢 Excellent |
| Revenue CAGR (3Y) * | ~55–60% | 🟢 Exceptional |
| Profit CAGR (3Y) * | ~100–120% | 🟢 Exceptional |
| Promoter Holdings (%) | N/A | — Check Screener |
| Pledging (%) | N/A | — Check Screener |
🟢 Green = Strong/Attractive | 🟡 Yellow = Moderate | 🔴 Red = Weak/Caution
* Revenue CAGR (3Y) and Profit CAGR (3Y) are analyst estimates based on reported financials and industry intelligence. All other metrics sourced from Screener.in live data.
🏆 About Futurecaps
Futurecaps is a SEBI-registered investment research platform trusted by thousands of retail investors across India for its rigorous, unbiased multibagger stock research. Our team of experienced analysts applies time-tested value investing frameworks — combining fundamental analysis, qualitative moat assessment, and risk management — to identify high-potential small and mid-cap stocks before they enter mainstream radar. Whether you’re a seasoned investor or just starting your wealth-creation journey, Futurecaps is your trusted research partner. Explore our free and premium research at futurecaps.com. 🏆
💡 About Value Investing
Value investing is the art of buying great businesses at fair or discounted prices — a philosophy pioneered by Benjamin Graham and perfected by Warren Buffett. The core idea is simple: every stock has an intrinsic value based on its earnings power, growth potential, and risk profile. When the market price falls below this intrinsic value, a margin of safety exists — that’s your opportunity. For KP Green Engineering, understanding the intrinsic value relative to its 123% EPS growth is critical. Use the Futurecaps Intrinsic Value Calculator to run your own numbers and make informed, confident investment decisions. 💡
🎁 Get FREE Multibagger Stock!
Join thousands of smart investors. Get our expertly researched FREE multibagger stock recommendation — absolutely free!