
💍 PC Jeweller Limited
📋 About PC Jeweller Limited
PC Jeweller Limited is one of India’s prominent jewellery retail companies, headquartered in New Delhi. Founded in 2005 by Padam Chand Gupta and Balram Garg, the company rapidly expanded to become a recognisable name in the Indian gold and diamond jewellery space. It operates through a chain of company-owned showrooms spread across major metros, Tier-1, and Tier-2 cities in India.
The company offers a wide range of jewellery including gold jewellery, diamond-studded pieces, silver ornaments, and precious stone jewellery — catering to bridal, festive, gifting, and everyday wear segments. PC Jeweller follows an integrated model where it handles design, manufacturing, and retail in-house, allowing it to maintain quality control and competitive pricing.
After facing a significant business downturn between FY19 and FY22 — marked by regulatory scrutiny, write-offs of export receivables, and a sharp fall in revenue — the company has been on a remarkable recovery path. It has restructured operations, nearly eliminated its debt, and refocused on domestic retail. As of 2026, PC Jeweller is rebuilding investor confidence with improved financial metrics and a leaner balance sheet. 💰
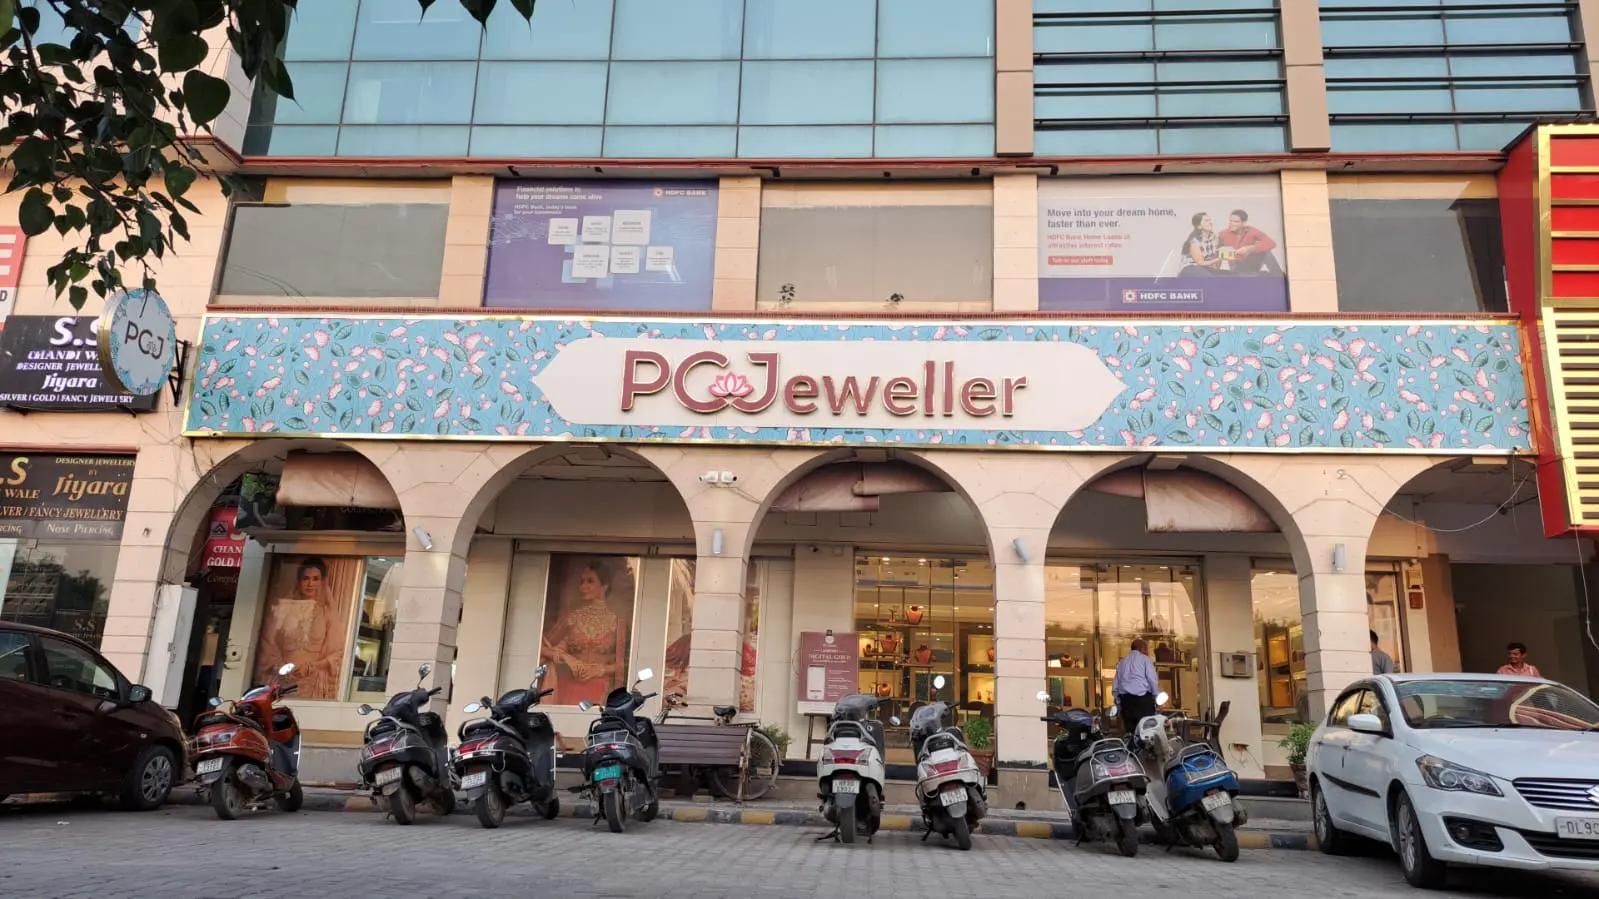
🌐 Official website: PC Jeweller Limited Official Website
🚀 Expansion Plans
PC Jeweller is steadily executing a strategic recovery and expansion roadmap that focuses on both domestic retail consolidation and product diversification. Here’s what the company’s growth direction looks like heading into 2026 and beyond:
- 📍 Showroom Network Expansion: The company is targeting a gradual expansion of its showroom footprint, with a focus on Tier-2 and Tier-3 cities in North, Central, and Western India — markets that are witnessing rapid urbanisation and rising disposable incomes. New showrooms are planned in states like Uttar Pradesh, Rajasthan, Haryana, and Madhya Pradesh.
- 💻 Digital & Omnichannel Push: PC Jeweller has been strengthening its online sales platform to capture the growing demand for jewellery purchases via e-commerce. Integration of virtual try-on tools and digital catalogues is part of its tech-forward retail strategy.
- 💍 Product Portfolio Diversification: The company is expanding its lightweight jewellery range, targeting working women and younger urban consumers who prefer daily-wear, affordable fine jewellery. It is also exploring the lab-grown diamond (LGD) segment, which is one of the fastest-growing categories in the global and Indian jewellery market.
- 🏭 Manufacturing Capacity Enhancement: To reduce turnaround time and improve margins, the company is investing in upgrading its manufacturing facilities, with an emphasis on improving productivity and design output.
- 🤝 Franchise Model Exploration: PC Jeweller is exploring a franchise-based expansion model that could accelerate its geographic reach without proportionally increasing capex — a capital-light strategy that could unlock faster growth.
- 🌍 NRI & Export Markets: With a past in jewellery exports (albeit that segment caused challenges), the company is cautiously exploring NRI-focused jewellery lines, targeting diaspora communities through curated collections.
These expansion efforts, backed by a nearly debt-free balance sheet, position PC Jeweller to compound its retail revenues meaningfully over the next 3–5 years. 🚀
✅ Key Positives
- ✅ Near Debt-Free Balance Sheet: With a D/E ratio of just 0.04, PC Jeweller has successfully shed the heavy debt burden that troubled it in earlier years. This gives it significant financial flexibility to invest in growth without worrying about interest obligations.
- ✅ Revenue Recovery Momentum: After years of contraction, the company has demonstrated consistent revenue growth since FY23, reflecting successful operational restructuring and renewed consumer demand for branded jewellery.
- ✅ Integrated Business Model: PC Jeweller controls its value chain from design and manufacturing to retail. This vertical integration enables better cost management, quality assurance, and faster product turnaround — giving it an edge over pure-play retailers.
- ✅ India’s Jewellery Market Tailwind: India is the world’s second-largest gold consumer. The long-term structural shift from unorganised to organised jewellery retail — accelerated by GST, hallmarking mandates, and digital payments — is a powerful macro tailwind that benefits listed players like PC Jeweller.
- ✅ Brand Rehabilitation: After the controversies of FY18–FY19, the management has taken concrete steps — auditor changes, regulatory compliance, write-offs — to clean up the books and restore credibility. This rerating of trust can be a powerful re-rating catalyst.
- ✅ Low Market Price Entry Point: At ₹15.1, the stock is trading at relatively modest valuations with a PE of 19.7x and PB of 1.6x — not demanding for a recovering consumer brand with improving fundamentals.
- ✅ Festive & Wedding Season Demand: India’s strong cultural affinity for gold jewellery during weddings and festivals creates recurring, predictable demand cycles that support revenue visibility for jewellery retailers.
- ✅ Growing Middle Class: India’s expanding middle class and rising per capita income are structural demand drivers for discretionary spending on jewellery, particularly in Tier-2 and Tier-3 markets that PC Jeweller is targeting.
⚠️ Key Concerns
- ⚠️ Low Promoter Holding: At just 39.11%, the promoter stake is below the comfort zone for many value investors, raising questions about skin-in-the-game and potential for future dilution.
- ⚠️ Reputation Overhang: The company’s history of accounting controversies and export receivable write-offs continues to weigh on investor sentiment and institutional interest.
- ⚠️ Low ROE & ROCE: Current ROE of 9.96% and ROCE of 9.57% are below the ideal 15%+ threshold, indicating the company is yet to reach optimal capital efficiency in its recovery phase.
- ⚠️ Modest EPS: An EPS of just ₹0.85 leaves limited earnings cushion. Any operational hiccup could quickly erode profitability at this scale.
- ⚠️ Competitive Pressure: Well-capitalised peers like Titan’s Tanishq and Kalyan Jewellers are expanding aggressively, making market share gains tougher for PC Jeweller.
🔍 SWOT Analysis
PC Jeweller’s SWOT profile in 2026 reflects a company in active turnaround. Its core strengths lie in a nearly debt-free balance sheet, integrated manufacturing, and an established brand in North India. However, weaknesses persist — low promoter holding, recovering ROE/ROCE, and historical governance concerns remain red flags. On the opportunity side, India’s booming organised jewellery market, the lab-grown diamond wave, and digital retail expansion offer compelling growth avenues. Meanwhile, threats from deep-pocketed competitors like Titan, gold price volatility, and regulatory risks must be watched closely by investors. 📊
💪 STRENGTHS
- Pan-India retail presence with 60+ owned showrooms in key cities and towns
- Integrated business model covering design, manufacturing, and retail for better margins
- Significantly reduced debt position with D/E ratio of just 0.04 — near debt-free
- Strong brand recall in North and Central India with loyal customer base
⚠️ WEAKNESSES
- Promoter holding at 39.11% is relatively low, raising governance concerns
- Past controversies around accounting practices and export receivables have dented investor trust
- Revenue recovery still in progress after major contraction during FY19–FY22 period
🚀 OPPORTUNITIES
- India’s organised jewellery market is growing rapidly as consumers shift from unorganised players post-GST
- Rising aspirational spending by India’s growing middle class and tier-2/3 city consumers
- Expansion into lab-grown diamonds and lightweight everyday jewellery segments
🔴 THREATS
- Intense competition from Tanishq (Titan), Kalyan Jewellers, Senco Gold, and regional chains
- Gold price volatility directly impacts margins and consumer demand cycles
- Regulatory scrutiny and any recurrence of past compliance or fraud-related issues
* SWOT is based on publicly available information and analyst estimates. Not a buy/sell recommendation.
📈 Profit & Loss (Last 5 Years)
PC Jeweller’s financials narrate a classic recovery story. After bottoming out in FY22 with subdued revenues near ₹980 crore, the company has shown consistent top-line and bottom-line improvement through FY23–FY25, with revenues estimated to cross ₹2,650 crore in FY26E. Net profit has recovered sharply from near-negligible levels to an estimated ₹750 crore in FY26E, reflecting improving operating leverage and cost discipline. The trajectory, while encouraging, still needs to sustain for multiple years to fully restore investor confidence. 📊
* Estimated figures in ₹ Crores. Source: Annual reports & public disclosures. Not guaranteed to be accurate.
🔴 Risk Factors
- 🔴 Gold Price Volatility: PC Jeweller’s inventory is heavily exposed to gold price fluctuations. A sharp correction in gold prices can lead to inventory losses and margin pressure, while elevated prices can dampen consumer demand.
- 🔴 Regulatory & Legal Risks: The company has had past brushes with enforcement agencies. Any fresh regulatory action or legal proceedings could severely impact stock price and business operations.
- 🔴 Working Capital Intensity: The jewellery retail business is inherently working capital intensive due to high inventory holding costs. Any tightening of credit conditions could strain operations.
- 🔴 Key Man Risk: The business is significantly influenced by its founding promoters. Any leadership instability could affect strategic direction and investor confidence.
- 🔴 Economic Slowdown Risk: Jewellery is a discretionary purchase. Any economic downturn, job market stress, or decline in consumer sentiment could directly hurt sales volumes and revenue growth.
- 🔴 Competition from Unorganised Sector: Despite GST-led formalisation, a large chunk of India’s jewellery market remains unorganised. Local jewellers competing on lower prices and customer relationships remain a persistent threat.
- 🔴 Currency Risk: Any exposure to imported raw materials (gold, diamonds) means that INR depreciation can increase input costs and compress margins if not hedged effectively.
📊 Value Investing Snapshot
| Metric | Value |
|---|---|
| Market Price (₹) | ₹15.1 |
| Mkt Cap (₹ Cr) 🟡 | ₹14,810 Cr |
| PE Ratio 🟡 | 19.7x |
| PB Ratio 🟡 | 1.6x |
| Intrinsic Value (₹) 🔴 | ₹13 |
| D/E Ratio 🟢 | 0.04 |
| ROE (%) 🔴 | 9.96% |
| ROCE (%) 🔴 | 9.57% |
| Revenue CAGR (3Y) 🟡 *estimated | ~28% |
| Profit CAGR (3Y) 🟢 *estimated | ~148% |
| Promoter Holdings (%) 🔴 | 39.11% |
| Pledging (%) 🟢 | N/A |
📌 *Revenue CAGR (3Y) and Profit CAGR (3Y) are analyst estimates based on available public disclosures and are not sourced from verified audited filings. All other metrics are based on verified market and financial data.
Legend: 🟢 Green = Strong/Attractive | 🟡 Yellow = Moderate | 🔴 Red = Weak/Caution
Mkt Cap: 🟢 < ₹10,000 Cr 🟡 ₹10,000 Cr – ₹1,00,000 Cr 🔴 > ₹1,00,000 Cr (1 lakh crore)
🏆 About Futurecaps
Futurecaps is a SEBI-registered investment advisory platform dedicated to empowering retail investors across India with high-quality, research-backed stock ideas. Trusted by thousands of smart investors, Futurecaps specialises in identifying multibagger opportunities — stocks with the potential to deliver outsized returns over the long term. Our team of experienced analysts uses a disciplined value investing framework to uncover undervalued companies with strong fundamentals and sustainable competitive advantages. Whether you’re a first-time investor or a seasoned market participant, Futurecaps provides the insights you need to make informed, confident investment decisions. 💡
💡 About Value Investing
Value investing is a time-tested investment philosophy popularised by Benjamin Graham and Warren Buffett. The core idea is simple: buy stocks trading below their intrinsic value and hold them until the market recognises their true worth. This approach prioritises fundamentals — earnings, cash flows, balance sheet strength, and competitive moats — over short-term price movements or market sentiment. A key tool in value investing is calculating a stock’s intrinsic value to determine whether it offers a sufficient margin of safety. Want to calculate intrinsic value yourself? Try the Futurecaps Intrinsic Value Calculator — it’s free and built for Indian retail investors. 📊
⚠️ Disclaimer
This article is prepared for informational and educational purposes only. It does not constitute investment advice, a solicitation, or a recommendation to buy or sell any securities. Futurecaps.com is a SEBI-registered investment advisor. Investing in equities involves risk, including possible loss of principal. Past performance is not indicative of future results. Please consult your financial advisor before making any investment decision.
🎁 Get FREE Multibagger Stock!
Join thousands of smart investors. Get our expertly researched FREE multibagger stock recommendation — absolutely free!