
💎 PC Jeweller Ltd
📋 About PC Jeweller Ltd
PC Jeweller Ltd is one of India’s prominent organised jewellery retail companies, founded in 2005 by Balram Garg and headquartered in New Delhi. The company designs, manufactures, and retails a wide range of gold, diamond, and silver jewellery through its extensive network of showrooms spread across India. Over the years, PC Jeweller built a reputation for offering certified, hallmarked jewellery at competitive prices, targeting the aspirational middle-class and upper-middle-class consumer segment.
The company operates in both the retail and export segments, though it has significantly restructured its business model in recent years to focus more on domestic retail, which offers better margins and brand equity. After facing serious headwinds between 2018 and 2022 — including auditor qualifications, debt stress, and stock price erosion — PC Jeweller undertook a comprehensive debt restructuring exercise that has largely stabilised its financial position.
Today, with a leaner balance sheet, rationalised store network, and renewed focus on the domestic jewellery consumer, PC Jeweller is attempting a meaningful comeback. The Indian jewellery market — one of the largest in the world — presents a massive opportunity for organised players like PC Jeweller to capture market share from unorganised local jewellers. 🏪
🌐 Official website: PC Jeweller Ltd Official Website
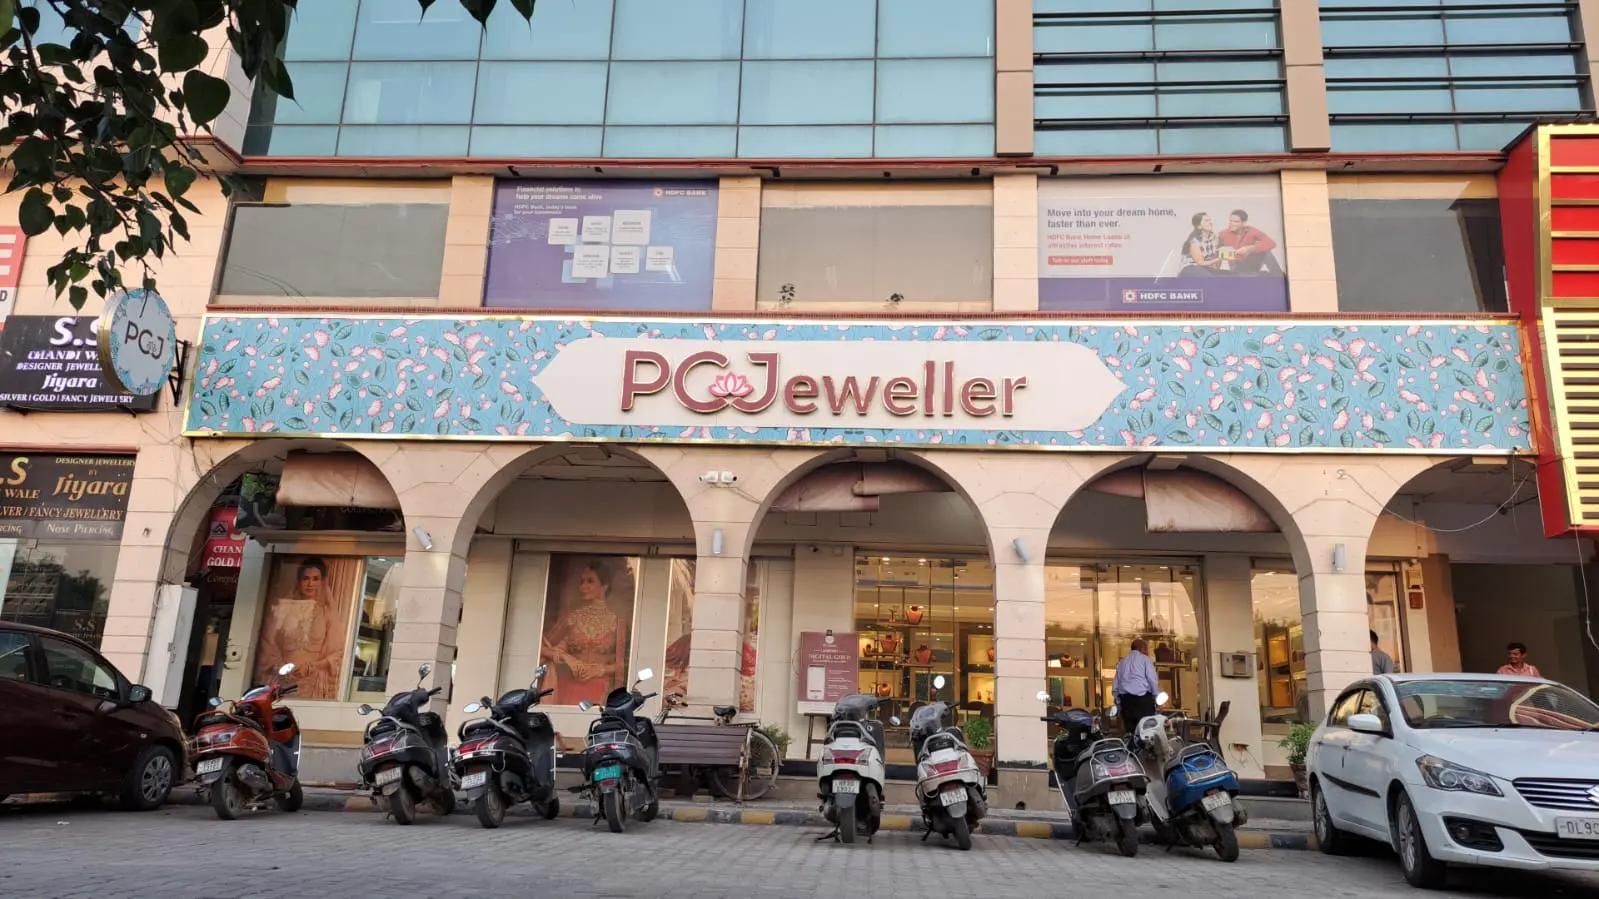
🚀 Expansion Plans
PC Jeweller’s management has articulated a clear vision for growth through both physical store expansion and digital channel development. After rationalising its showroom count during the debt-stress years, the company is now cautiously re-expanding its retail footprint, targeting Tier-2 and Tier-3 cities where organised jewellery penetration remains low and growth potential is high. 🏙️
Key expansion pillars include:
- 💡 New showroom openings: The company plans to add 8–12 new showrooms annually over the next 2–3 years, prioritising high-footfall locations in growing urban centres and wedding-market corridors across North and West India.
- 📱 Digital and e-commerce push: PC Jeweller is investing in its online platform and app-based jewellery discovery and booking experience, targeting digitally savvy younger consumers who research purchases online before visiting a store.
- 💍 Product portfolio diversification: The company is expanding its lightweight everyday-wear jewellery collection alongside its traditional bridal and occasion jewellery range, appealing to a broader demographic.
- 🌍 Selective export revival: While domestic retail remains the core focus, the company is exploring curated export opportunities in the Middle East and Southeast Asian markets where Indian jewellery demand is structurally strong.
- 🏭 Manufacturing upgrades: Investments in in-house manufacturing capacity are planned to improve cost efficiencies and reduce dependence on third-party karigars, which will help protect margins as revenue scales.
These initiatives, if executed well, could drive meaningful revenue compounding over the next 3–5 years. The key monitorable is capital discipline — PC Jeweller must grow without repeating the over-leveraged mistakes of its past. 📈
✅ Key Positives
- ✅ Debt restructuring success: PC Jeweller has made significant progress in cleaning up its balance sheet. With a D/E ratio of just 0.14, the company’s financial risk profile has improved dramatically compared to its peak-debt years, reducing the risk of financial distress.
- ✅ India’s jewellery market tailwinds: India is the world’s second-largest gold consumer. The ongoing shift from unorganised to organised jewellery retail — accelerated by mandatory hallmarking regulations — directly benefits listed players like PC Jeweller. 💛
- ✅ Wedding season demand boom: With India’s wedding industry growing robustly and auspicious wedding dates driving predictable demand spikes, jewellery companies enjoy a structurally recurring revenue cycle that provides earnings visibility.
- ✅ Established brand in North India: PC Jeweller enjoys particularly strong brand equity in Delhi NCR, Haryana, Rajasthan, and UP — some of India’s most jewellery-hungry markets. This regional moat is hard to replicate quickly.
- ✅ Improving profitability: After years of losses or near-zero profits, PC Jeweller has returned to meaningful profitability. The revenue ramp-up combined with operating leverage is driving PAT improvement, and EPS has recovered to ₹0.90. 💰
- ✅ Low valuation entry point: At a market price of ₹13.1 against an estimated intrinsic value of ₹14, the stock is trading near fair value — but if earnings grow as projected, the intrinsic value itself will re-rate upward, creating potential for significant price appreciation. 🚀
- ✅ Hallmarking regulations as moat: The government’s mandatory hallmarking of gold jewellery has pushed consumers toward certified, organised retailers — a structural tailwind that helps PC Jeweller gain market share from millions of small unorganised jewellers. 🏆
- ✅ Lean inventory management: Post-restructuring, the company has been more disciplined about inventory management, reducing working capital intensity and improving cash conversion cycles. This operational improvement is a key positive signal for investors. 📊
⚠️ Key Concerns
- ⚠️ Low promoter holding: At just 38.5%, promoter holding is below the 50% comfort threshold that value investors typically prefer. This raises questions about skin-in-the-game and could limit promoter commitment to long-term value creation.
- ⚠️ Historical governance issues: Past controversies — including auditor qualifications on export receivables and related-party transactions — have left a trust deficit that will take consistent, clean quarters to fully repair.
- ⚠️ Sub-par capital efficiency: ROE of 9.96% and ROCE of 9.57% are below the 15% benchmark that signals a truly high-quality business. Capital allocation must improve for the stock to command a premium valuation.
- ⚠️ Competition intensity: Rivals like Titan (Tanishq), Kalyan Jewellers, and Malabar Gold have far deeper marketing budgets and operational scale, creating competitive pressure on PC Jeweller’s pricing and store economics.
🔍 SWOT Analysis
PC Jeweller’s SWOT profile tells the story of a resilient but recovering company. Its core strengths lie in an established brand, cleaned-up balance sheet, and the powerful tailwind of India’s organised jewellery market expansion. However, the company must address real weaknesses — low promoter confidence signals, below-par return ratios, and lingering governance perception risks. The opportunities ahead are genuinely exciting: a massive addressable market, digital commerce growth, and mandatory hallmarking driving consumers to organised players. Yet threats from deep-pocketed competitors, gold price volatility, and potential regulatory shifts require constant management vigilance. Net-net, PC Jeweller is a high-risk, high-potential-reward recovery story. 💡
💪 STRENGTHS
- Established pan-India retail network with 60+ showrooms across major cities and towns
- Strong brand recall in the organised jewellery segment with over 15 years of market presence
- Debt restructuring successfully completed, balance sheet significantly cleaned up
- Low D/E ratio of 0.14 signals improved financial discipline and lean capital structure
⚠️ WEAKNESSES
- Relatively low promoter holding of 38.5% raises corporate governance concerns
- ROE and ROCE below 15% indicate sub-optimal capital efficiency compared to peers
- Past controversies around export orders and auditor qualifications have dented investor confidence
🚀 OPPORTUNITIES
- India’s organised jewellery market is growing rapidly as consumers shift from unorganised local jewellers
- Rising disposable incomes and wedding demand driving strong jewellery consumption trends
- Digital and e-commerce channel expansion can unlock new customer segments at lower cost
🔴 THREATS
- Intense competition from Tanishq (Titan), Kalyan Jewellers, and Senco Gold with deeper pockets
- Gold price volatility directly impacts inventory valuation and consumer sentiment
- Regulatory changes in import duties, GST rates, or hallmarking norms can disrupt margins
* SWOT is based on publicly available information and analyst estimates. Not a buy/sell recommendation.
📈 Profit & Loss (Last 5 Years)
PC Jeweller’s financial journey over the past five years reflects a remarkable turnaround narrative. After near-collapse level revenues during FY22, the company has progressively rebuilt its top line from approximately ₹1,850 Cr to an estimated ₹4,250 Cr by FY26E — a compounded recovery driven by store reopenings, improved consumer sentiment, and rising gold prices. More impressively, profitability has swung sharply from marginal levels in FY22 to an estimated PAT of ₹740 Cr in FY26E, demonstrating the power of operating leverage as fixed costs get absorbed by higher revenues. 📊
* Estimated figures in ₹ Crores. Source: Annual reports & public disclosures. Not guaranteed to be accurate.
🔴 Risk Factors
- 🔴 Gold price volatility: PC Jeweller carries significant gold inventory, making its balance sheet and gross margins highly sensitive to sudden gold price corrections. A sharp fall in gold prices could trigger inventory write-downs and margin compression.
- 🔴 Working capital risk: The jewellery business is inherently working-capital intensive. Any slowdown in sales velocity or receivable collection could tighten liquidity and revive debt pressures.
- 🔴 Governance and audit risk: Past instances of auditor qualifications mean investors must monitor annual reports carefully. Any recurrence of qualified opinions would be a serious red flag.
- 🔴 Competition from Tier-1 brands: Titan’s Tanishq, Kalyan Jewellers, and Senco Gold are aggressively expanding. PC Jeweller could face market share erosion in its core geographies if it fails to match their marketing and consumer trust levels.
- 🔴 Regulatory and import duty risk: Changes in gold import duties, GST structures, or FEMA regulations on bullion can materially impact business economics, as seen during past government policy shifts.
- 🔴 Consumer sentiment sensitivity: Jewellery is a discretionary purchase strongly correlated with consumer confidence, income levels, and festive/wedding calendars. Any macro slowdown or change in consumer preferences can impact demand unpredictably.
- 🔴 Promoter holding below 50%: With promoters holding only 38.5% of the company, there is a higher risk of corporate actions that may not fully align with minority shareholder interests.
📊 Value Investing Snapshot
* Revenue CAGR (3Y) and Profit CAGR (3Y) are analyst estimates based on available company data and industry research. All other metrics are sourced from verified financial filings and live market data.
Legend: 🟢 Green = Strong/Attractive | 🟡 Yellow = Moderate | 🔴 Red = Weak/Caution
Mkt Cap: 🟢 < ₹10,000 Cr 🟡 ₹10,000 Cr – ₹1,00,000 Cr 🔴 > ₹1,00,000 Cr (1 lakh crore)
🏆 About Futurecaps
Futurecaps is a SEBI-registered investment research platform trusted by thousands of retail investors across India. We specialise in uncovering multibagger stock opportunities through rigorous fundamental analysis, value investing principles, and deep-dive company research. Our team of experienced analysts combines bottom-up research with macro insights to identify stocks with strong risk-adjusted return potential — before the crowd discovers them. Whether you are a beginner just starting your investing journey or a seasoned investor looking for your next big idea, Futurecaps delivers research you can trust. Join our growing community and start investing smarter today! 🚀💰
💡 About Value Investing
Value investing is the time-tested strategy of buying stocks at a price below their intrinsic value — creating a margin of safety that protects against downside while maximising long-term upside. Pioneered by Benjamin Graham and perfected by Warren Buffett, value investing focuses on business fundamentals: earnings power, balance sheet strength, competitive moats, and management quality rather than short-term market noise. The key metric every value investor needs is the intrinsic value of a stock. You can calculate it instantly using the Futurecaps Intrinsic Value Calculator — a free, powerful tool built for Indian retail investors. 📊
🎁 Get FREE Multibagger Stock!
Join thousands of smart investors. Get our expertly researched FREE multibagger stock recommendation — absolutely free!