
In this article, we can see Can Fin Homes as a Potential Multibagger Stock as on July 2024.
Can Fin Homes
Can Fin Home is a public deposit-taking housing finance company. It focuses on funding to low & middle group individuals & first-time homebuyers preferably salaried or professional
The company has 3 major segments: Housing finance, Non-housing Finance & Deposits. The average ticket size is 18 lacs for housing loans & 9 lacs for non-housing loans. It also accepts – Fixed & Cumulative deposits as per the rules of the National Housing Bank. Shri Suresh S Iyer is the current Managing Director & CEO.
Website
Location
Can Fin Home headquartered in Bengaluru. The branch network increased from 140 to 198 as on 184 branches+ 21 affordable housing loan centers + 14 satellite offices over 100 cities spread across 21 states.
Products & Services
- Housing finance
- Non-housing Finance
- Deposits.
POSITIVES
- Average cost of borrowings remains at 6.5%, and consistently delivering steady spreads over the past five years.
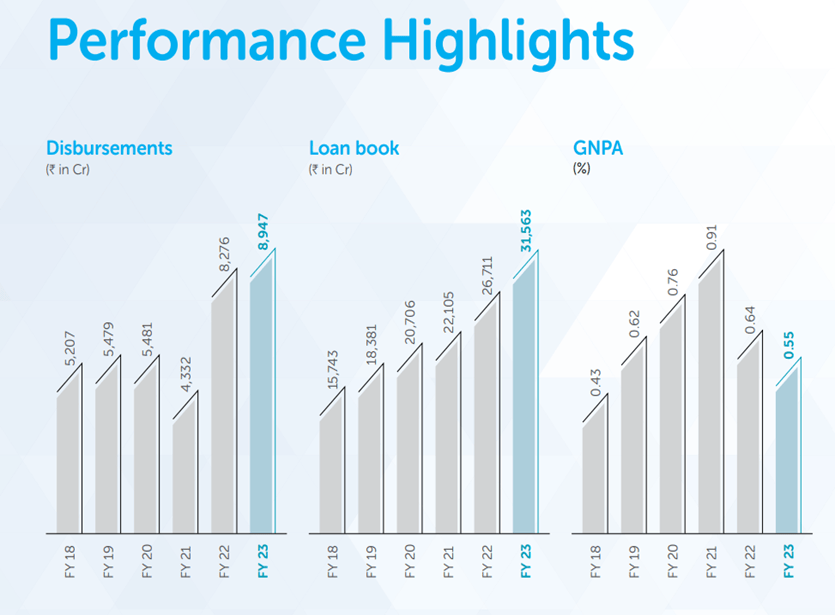
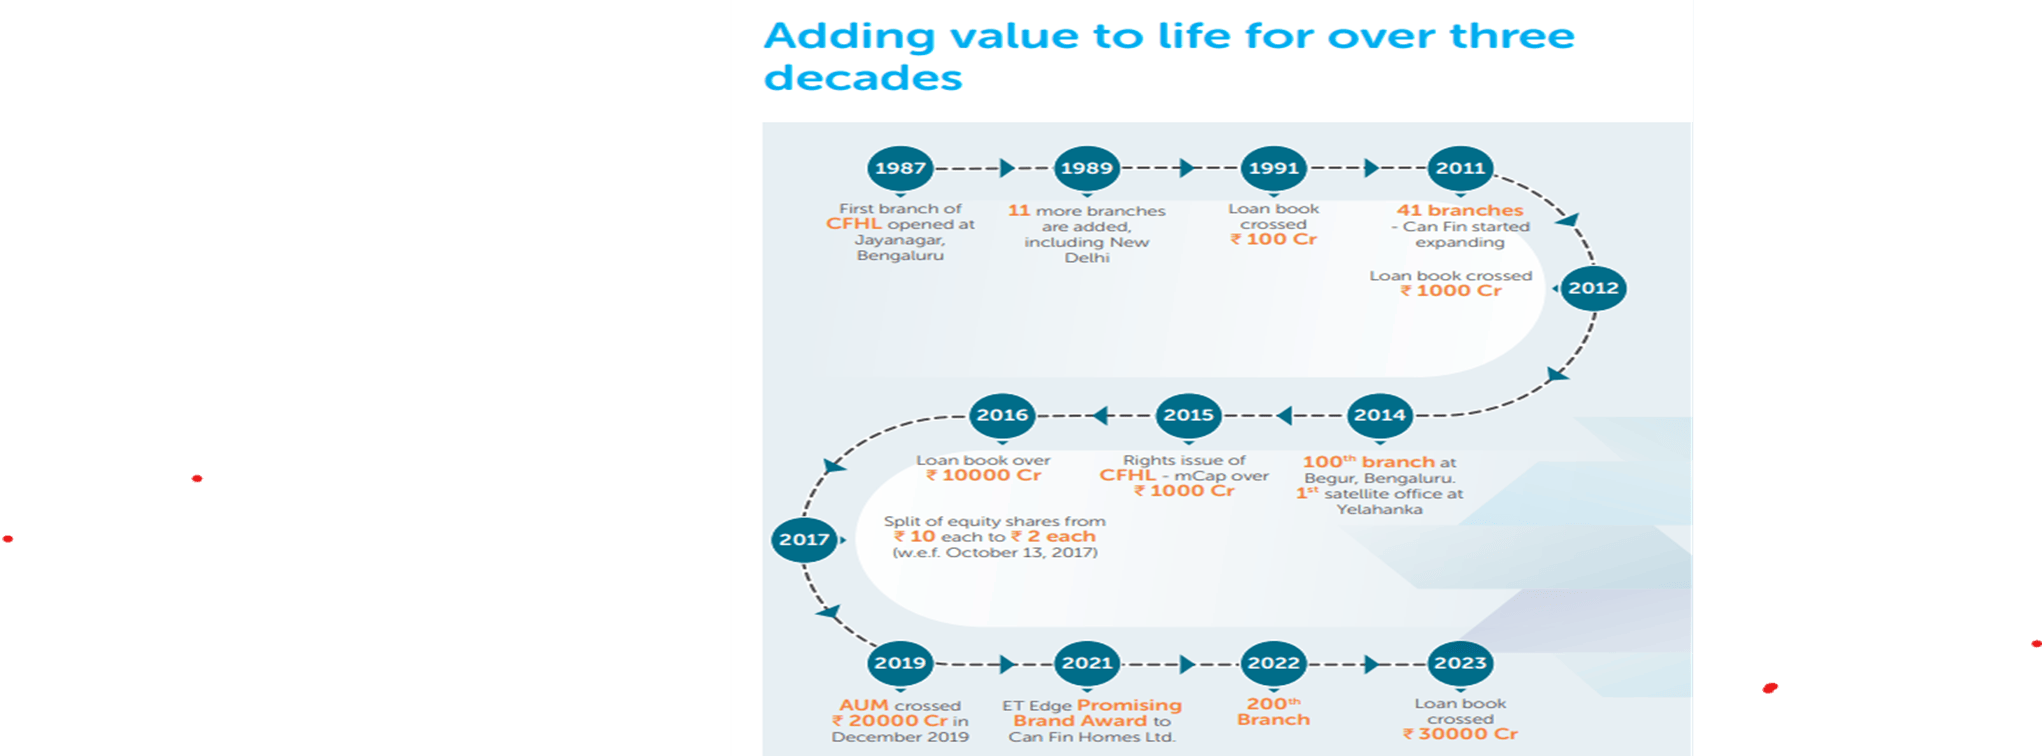
- Loan book crossed 30000 Crores which depicts growth in business.
- The Company plans to expand its branch network and make inroads into new, potential geographies to extend housing finance to a diverse segment of home aspirants.
- Strong balance sheet offers necessary resources for funding expansion, improving customer service and developing new products and services.
- Deliver returns and consistent dividend payouts by focusing on the existing operations and by exploring new opportunities.
- Earnings have grown by 17.1% per year over the past 5 years.
- Can Fin Homes Ltd. has 205 branches spread over 21 States and Union Territories catering to the different needs of the borrowers across geographies.
- The share of loans extended to self employed stood at 27% of the loan book, totalling H8477 crore.
- A healthy asset quality increases the profitability, net worth and CRAR, which in turn improves the Company’s growth and promotes its goodwill in the market.
- Controlling funding costs, positively impact the Company’s bottom line, leading to improved profitability and financial performance.
- Can Fin Homes is a dividend paying company with a current yield of 0.9% that is well covered by earnings. Next payment date is on 6th September, 2024 with an ex-dividend date of 18th July, 2024.
- Company dividend payments have increased over the past 10 years.
- Company dividend (0.9%) is higher than the bottom 25% of dividend payers in the Indian market (0.26% With its low payout ratio (10.6%), 511196’s dividend payments are thoroughly covered by earnings.
- ADD Intrinsic Value Discount 30%.
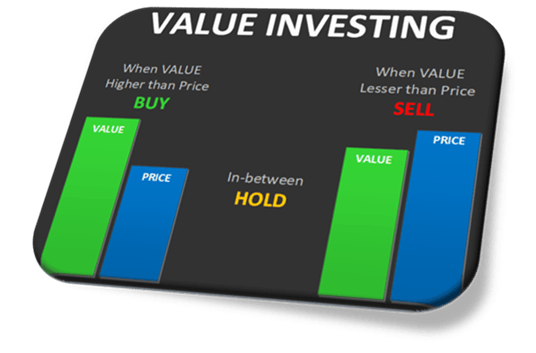
Value Investing
- The company is good value based on its Price-To-Earnings Ratio (15X) compared to the peer average (24x).
- The Company has good value based on its Price-To-Earnings Ratio (15.8x) compared to the Indian Diversified Financial industry average (28.9x).
- Can Fin Homes is forecast to grow earnings and revenue by 13.6% and 14.7% per annum respectively. EPS is expected to grow by 13.6% per annum. Return on equity is forecast to be 17.9% in 3 years
- Revenue (14.7% per year) is forecast to grow faster than the Indian market (9.6% per year). Earnings vs Savings Rate: Company forecast earnings growth (13.6% per year) is above the savings rate.
Profit & Loss
| Mar-21 | Mar-22 | Mar-23 | CY | |
| Revenue | 2,018 | 1,988 | 2,742 | 3,523 |
| Interest | 1,209 | 1,155 | 1,702 | 2,231 |
| Expenses | 182 | 189 | 205 | 323 |
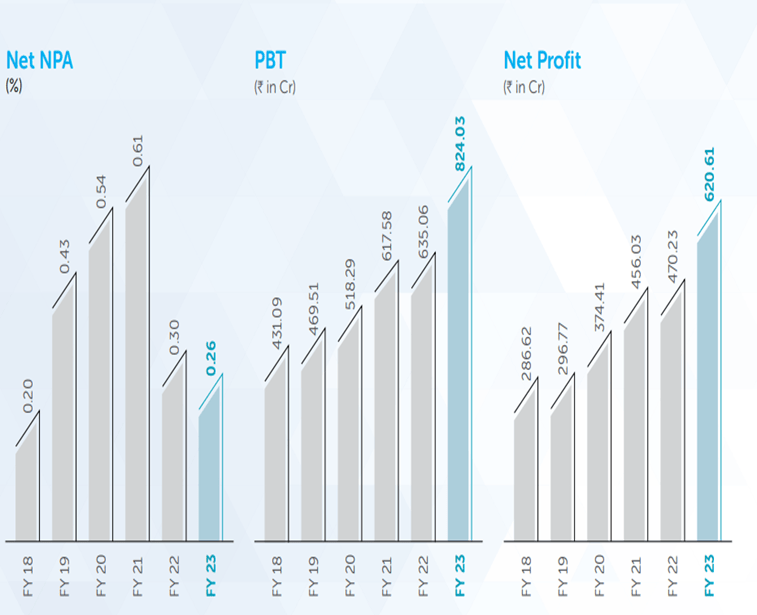
| Financing Profit | 627 | 644 | 835 | 969 |
| Financing Margin % | 31% | 32% | 30% | 27% |
| Other Income | 0 | 1 | 1 | 2 |
| Depreciation | 10 | 10 | 12 | 13 |
| Profit before tax | 618 | 635 | 824 | 958 |
| Tax % | 26% | 26% | 25% | 22% |
| Net Profit | 456 | 471 | 621 | 751 |
Negatives
- Housing finance companies (HFCs) face significant competition from banks and large housing finance companies in Tier I and Tier II cities.
- Credit Risk is an intrinsic part of any lending activity and arises on account of payment default of instalments by the borrowers.
- Risks which depend on external factors such as inflation, deflation, demand, supply dynamics are beyond the control of the Company. The adverse market conditions give scope for liquidity risk, interest rate risk, funding risk etc.
- Liquidity risk is a risk of not having sufficient funds to meet the financial commitments. It arises mainly when there is an overdependence on the market borrowings and the market situation is not conducive.
- Company is underperformed the Indian Diversified Financial Industry which returned 68.4% over the past year.
- Some employees did Fraudulent transactions affecting the business & reputation of the bank. link.
Warren Buffett Checklist
| Type | Value |
| ECONOMIC MOAT | Moderate |
| GROWTH | Good |
| VALUATION | Good |
| DEBT | High |
| INTEGRITY | Moderate |
Summary
The company has the potential to become multibagger in the order of 300-500% in 5-10 year term.
SIGN-UP FREE Multibagger Stock
SIGN-UP to get FREE Multibagger Stock immediately based on Value Investing principles. Futurecaps created Mazagon Dock 20X & Bajaj Finance 80X Returns under same principles. Performance.

Multibagger with Expansion Plans | Low PE Ratio | Low Book Value Ratio | Intrinsic Value Discount 70 % | PLUS Free Value Investing Education