
In this article, we can see Zomato as a Potential Multibagger Stock as on August 2024.
Zomato
Zomato Limited is one of the leading online Food Service platforms in terms of the value of food sold. Its offerings include food delivery, dining-out services, Loyalty programs, and others.
The company has established a strong footprint across 23 countries with 131,233 active food delivery restaurants, 161,637 active delivery partners, and an average monthly food order of 10.7 million customers.
Its mobile application is the most downloaded food and drinks application in India in each of the last three fiscal years on iOS App Store and Google Play combined. App gets 90 billion monthly visits as of FY23 In India. Deepinder Goyal is the Founder, MD & CEO.
Website
Location
Zomato had 389,932 Active Restaurant Listings. The company is active in 1000+ cities with 500+ cities added in FY22.
Products & Services
- Food delivery
- Dining out
- Hyper pure
POSITIVES OF ZOMATO TO BECOME A MULTIBAGGER
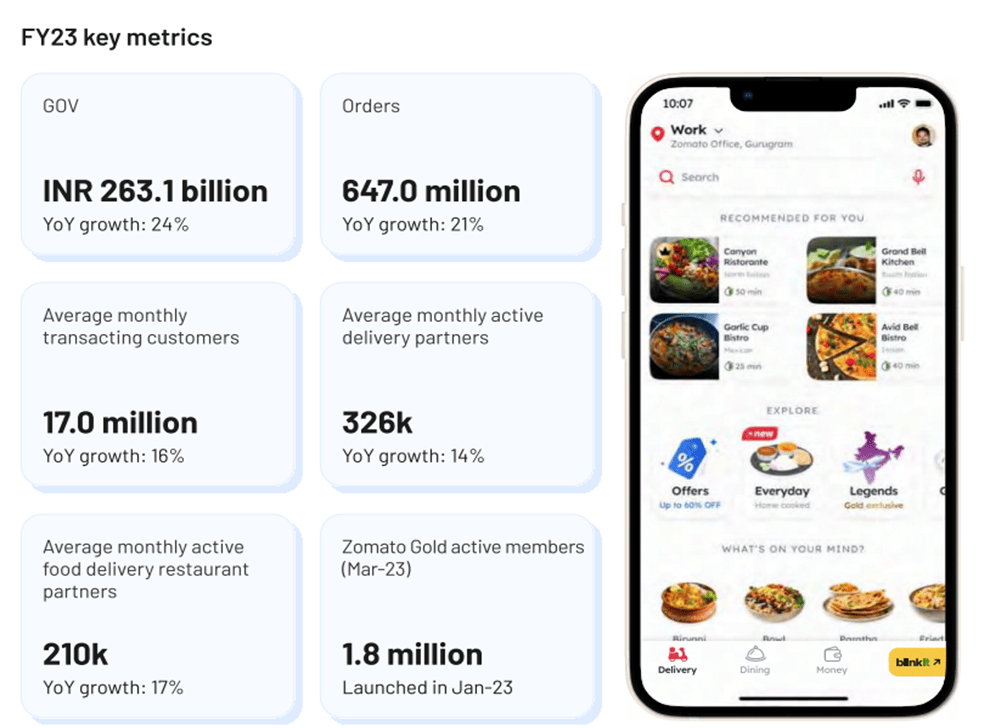
- Relaunched Zomaland, food and entertainment carnival in FY23, post the pandemic, across 7 cities in India. Average monthly active delivery partners grew by 14% YoY to 326k in FY23.
- Company collaborates with restaurants to provide exclusive deals and offers to its customers. These promotions can range from discounts on food bills to special set menus or limited time offers.
- In FY23, Others primarily included (1) dining-out offering in India and UAE, (2) Zomato Live and (3) other initiatives including food delivery services offered to Talabat in UAE, among others.
- Adjusted Revenue grew 57% Year-on-Year (“YoY”) to INR 86.9 billion in FY23 from INR 55.4 billion in FY22.
- Adjusted EBITDA margin improved to -9% in FY23 from -18% in FY22, largely driven by the improving profitability in the food delivery business.
- In FY23, the Company reported a positive Adjusted EBITDA for the Zomato business (excluding quick commerce) of INR 0.28 billion as compared to a loss of INR 2.25 billion a year ago in Q4FY22.
- Average monthly active food delivery restaurant partners increased by 17% YoY to 210k in FY23. ended this fiscal with 215k average monthly active food delivery restaurant partners in Q4FY23.
- Hyperpure revenues grew to INR 15.1 billion (180% YoY) in FY23 driven by both addition of new customers as well as increase in spends of existing customers on platform.
- Company is having expanding presence in India through the Rapid Urbanization, Availability of Faster & Affordable Internet facilities thereby 30% CAGR future growth possible in Revenue & Profits.
What makes Zomato To Become a Value Investing Company
- The company is trading at 300+ PE Ratio due to the Low Profit margin it make.
- A company may face a loss of brand perception and reputation due to several factors, including negative publicity or feedback on various platforms.
- The company’s share price has been volatile over the past 3 months.
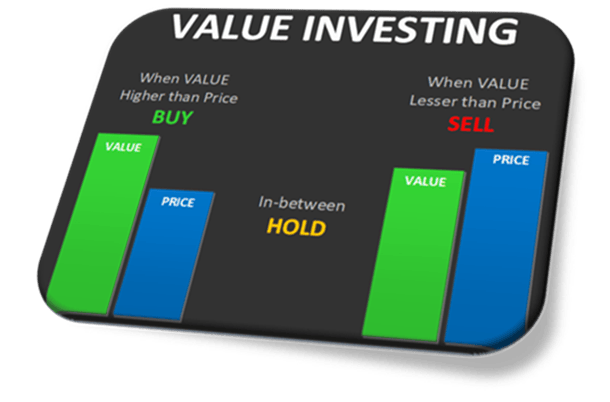
- ZOMATO (₹262.34) is trading above our estimate of fair value (₹70.91).
- Promoter holdings is 0% for Zomato given the fact of selling holdings.
Profit & Loss
| Mar-21 | Mar-22 | Mar-23 | CY | TTM | |
| Sales | 1,994 | 4,192 | 7,079 | 12,114 | 13,904 |
| Expenses | 2,461 | 6,043 | 8,290 | 12,072 | 13,637 |
| Operating Profit | -467 | -1,851 | -1,211 | 42 | 267 |
| OPM % | -23% | -44% | -17% | 0% | 2% |
| Other Income | -200 | 793 | 682 | 847 | 902 |
| Interest | 10 | 12 | 49 | 72 | 79 |
| Depreciation | 138 | 150 | 437 | 526 | 545 |
| Profit before tax | -815 | -1,220 | -1,015 | 291 | 545 |
| Tax % | 0% | 0% | -4% | -21% | |
| Net Profit | -816 | -1,222 | -971 | 351 | 602 |
Negatives
- Company is trading at 300+ PE Ratio due to the Low Profit margin it make.
- Company may face a loss of brand perception and reputation due to several factors, including negative publicity or feedback on various platforms.
- ZOMATO’s share price has been volatile over the past 3 months.
- ZOMATO (₹262.34) is trading above our estimate of fair value (₹70.91).
- Promoter holdings is 0% for Zomato given the fact of selling holdings.
- ZOMATO is expensive based on its Price-To-Sales Ratio (16.3x) compared to the peer average (5.6x).
- ZOMATO’s Return on Equity is forecast to be low in 3 years time (15.4%).
- ZOMATO has become profitable in the last year, making the earnings growth rate difficult to compare to its 5-year average.
- ZOMATO’s Return on Equity (3%) is considered low.
Warren Buffett Checklist
| Type | Value |
| ECONOMIC MOAT | GOOD |
| GROWTH | GOOD |
| VALUATION | BAD |
| DEBT | GOOD |
| INTEGRITY | GOOD |
Summary
The company has the potential to become multibagger in the order of 300-500% in 5-10 year term.
YOU WILL GET 4 MULTIBAGGER REPORTS IMMEDIATELY ON PAYMENT CLICK HERE FOR DISCOUNTED LINK https://wa.me/91884885831
OUR VFX MULTIBAGGER – HIGH GROWTH COMPANY- HOLLYWOOD CLIENTS
SIGN-UP FREE Multibagger Stock
SIGN-UP to get FREE Multibagger Stock immediately based on Value Investing principles. Futurecaps created Mazagon Dock 20X & Bajaj Finance 80X Returns under same principles. Performance.

Multibagger with Expansion Plans | Low PE Ratio | Low Book Value Ratio | Intrinsic Value Discount 70 % | PLUS Free Value Investing Education